
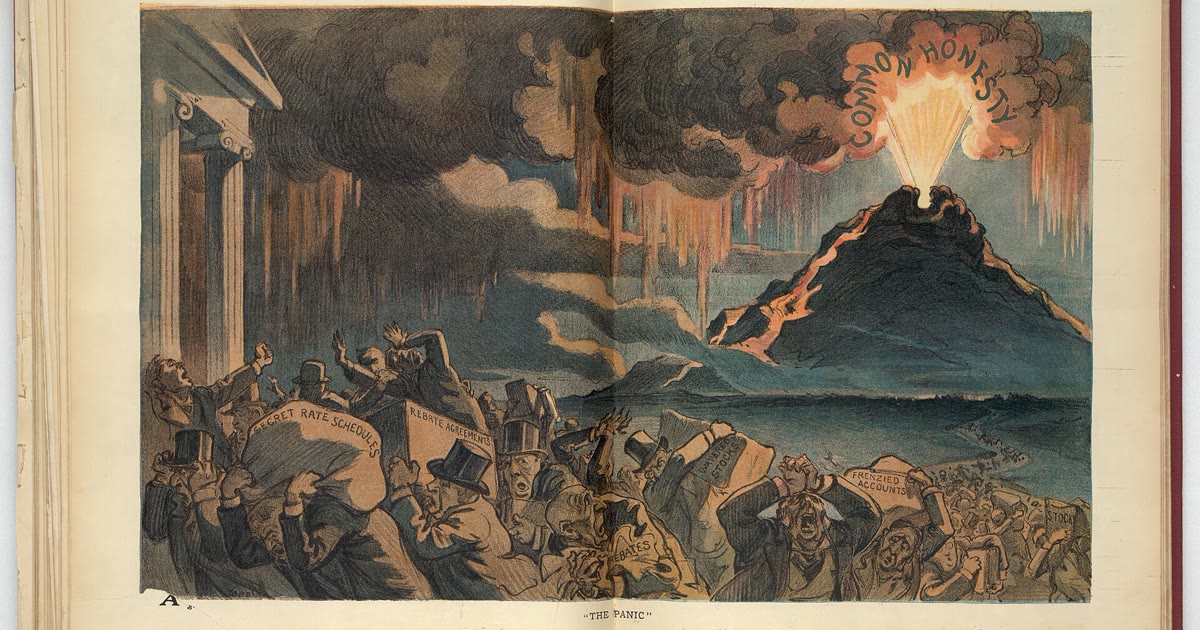
On 22 October 1907, depositors lined Fifth Avenue at the Knickerbocker Trust Company and kept lining up until the till could not meet the crowd, so the trust suspended payments. Within two days call money — the overnight credit that clears Wall Street — spiked toward twenty-five percent and higher, and the New York Stock Exchange nearly shut for want of cash to settle trades. Gold still defined the dollar. What failed was cash at the door.
The run sat on New York trust companies, and private bankers led by J. Pierpont Morgan’s group organized emergency support because no public central bank existed to lend. The Federal Reserve did not cause that October. Congress created the Fed afterward, in 1913, because the panic had shown how thin the country’s crisis plumbing was.
How the run began
The week had already cracked around a failed copper corner linked to F. Augustus Heinze and Charles Morse, so banks and trusts tied to those names looked weak. Depositors did not wait for slow audits. They wanted notes they could spend that day.
Knickerbocker’s suspension turned fear into a route map. Runs moved to other trusts and into the call-money market that funded broker loans, and once a crowd forms, payment slows and rumor names the next door. Without a backstop that can lend against good assets, solvent firms can fail for lack of cash in the hour they need it.
That is ordinary panic mechanics, which is why the episode still matters. The United States had no standing public lender of last resort with a legal duty to supply emergency liquidity to the whole banking field. Metal still settled contracts in the wider monetary order. Access to cash at the point of panic did not.
Why the trusts were the weak point
National banks in New York belonged to the Clearing House, so members could pledge good paper and borrow cash overnight through that club. Trust companies took deposits and made loans, but many sat outside the Clearing House and had no automatic seat at the table that recycled liquidity during a run.
That gap decided who survived the first days. When Knickerbocker’s condition looked bad, Clearing House support was refused and the line moved to other trusts. Institutions inside the club had a path to emergency cash. Trusts outside it became the panic’s weak point.
Trusts had grown quickly in the years before 1907, offering deposit-like liabilities and competing for business that looked like banking, while regulation and mutual aid did not keep pace. In a calm year the gap stayed invisible. In October it became the map of the crisis.
So 1907 is not a story that “gold failed.” Metal still defined the monetary unit. The plumbing failed, because trusts held large runnable liabilities without the same mutual support that national banks could tap through the Clearing House.
A private last resort
In the crisis weeks Morgan’s library at 219 Madison Avenue became a private command post, where bankers met, books were checked, and pools were pledged. Some firms received support. Knickerbocker stayed closed. Gold imports and Treasury deposits helped at the margins.
None of this needs a hero. A private coalition acted as a temporary last resort because statute had not built one, and that fact later shaped the politics of reform. A country that had needed one man’s library to keep the Exchange open was ready to argue for a public facility, even if it argued for years about who should control it.
A short timeline, 1907–1913
The Fed came after the panic, not before it.
- Early October 1907: Copper speculation tied to Heinze and Morse breaks; linked banks and trusts look fragile.
- 22 October 1907: Knickerbocker Trust faces a run and suspends payments.
- 23–24 October 1907: Runs spread among trusts; call money spikes; the Exchange nearly closes.
- Late October 1907: Morgan’s group and allied banks organize pools to support solvent firms, steady trust runs where possible, and keep the market open.
- May 1908: Aldrich-Vreeland Act allows emergency national-bank notes against broader collateral and creates the National Monetary Commission.
- November 1910: Senator Nelson Aldrich and a small group meet on Jekyll Island, Georgia, to draft a reserve-association plan. That meeting is design folklore, not a statute.
- 1912–1913: Pujo hearings attack the “Money Trust”; political wrapping of reform shifts toward regional reserve banks.
- 23 December 1913: President Woodrow Wilson signs the Federal Reserve Act.
What Congress built afterward
Aldrich-Vreeland (1908) was the first legislative answer. Groups of national banks could issue emergency currency against assets other than only government bonds, and the same law funded a National Monetary Commission to study a permanent system.
The commission toured Europe and studied banks that already had a legal last window. The Aldrich Plan that followed imagined a central reserve association with banker influence and elastic note issue, and public politics rejected a design that looked too much like Wall Street’s private club with a federal seal.
The Federal Reserve Act of 1913 created regional Federal Reserve Banks and a federal board structure, so member banks could discount commercial paper and receive Reserve notes. The public brief was elastic currency and a lender of last resort for banks, which meant an October run would not have to depend on one private library.
Jekyll Island was a drafting meeting in the commission years, not the law. The statute is the December 1913 Act. Morgan’s rescue was a private stand-in for a public facility that did not yet exist, and nobody at the time wanted the next October to depend on one man’s library again.
A lender built for the wrong year
The regional Reserve Banks opened in November 1914, by which time war had already closed the peacetime gold window across Europe. The Fed was designed for a trust-company run on Fifth Avenue, and it arrived in time for the end of the classical gold standard — a different kind of crisis, on a different scale.
The order of events runs one way. The Fed did not cause Knickerbocker’s run. Knickerbocker’s run helped make a Fed look necessary to Congress. Six years separate a crowd on the pavement from a signature at the White House, and in between sit a stopgap statute, a commission, a meeting on an island, and hearings on a Money Trust.