
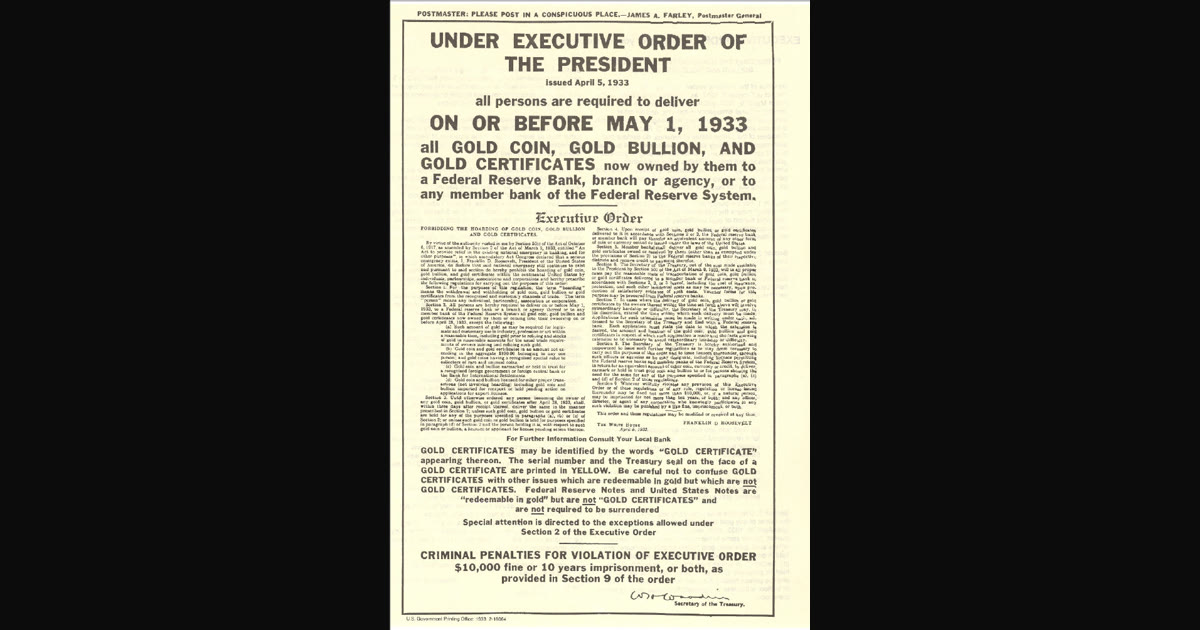
On 5 April 1933, Franklin Roosevelt signed Executive Order 6102, and most gold coin, gold bullion, and gold certificates in private American hands had to be delivered to a Federal Reserve Bank, a member bank, or a Treasury agent — at $20.67 an ounce, by a deadline printed as 1 May. Gold had already been leaving the banks in the week before inauguration, and a national bank holiday had stopped ordinary payments. The order made that call formal.
The Gold Reserve Act of 1934 then vested title to monetary gold in the United States and reset the official price from $20.67 to $35 an ounce. With that, the public claim on gold at the old mint price was gone, and official gold became a Treasury asset rather than circulating money.
Delivery at the old mint price
Persons in the United States had to turn in most gold coin, gold bullion, and gold certificates, and the payment was the official price then in force, $20.67 an ounce. Later licenses and exemptions matter more than that May date alone, because they decided who could still hold metal after the deadline.
The order did not take every ounce in private hands. Industry, profession, art, small personal amounts, and rare coins were excepted, but failing to deliver the monetary gold the order did cover was a federal offence. Compliance was incomplete. The legal requirement still stood, and the next January a statute changed both the title and the official price.
The bank holiday and the power to call gold
On 6 March 1933 a national bank holiday stopped ordinary payments. Gold exports and gold payments were constrained with the banks themselves. The Emergency Banking Act of 9 March 1933 ratified the holiday and gave the President broad power over gold, silver, and foreign exchange during the emergency.
That March statute is the legal floor under Order 6102. The order used a power Congress had just written. Banks reopened under license. Gold that had been a customer’s coin became, by stages, a thing the Treasury could call in.
In May, the Thomas Amendment to the Agricultural Adjustment Act added another lever: the President could reduce the gold content of the dollar by as much as fifty percent. The public still faced a delivery order at $20.67. The statute already contemplated a lighter gold dollar. That is not yet the $35 price.
Gold clauses, then the Gold Reserve Act
On 5 June 1933 a Joint Resolution of Congress declared gold clauses against public policy. A promise to pay in gold coin, or in a sum measured by gold, was to be discharged in legal tender. The Supreme Court later upheld the main line of that policy in the Gold Clause Cases of 1935. Once gold could be called in, gold-denominated private contracts could not stand as a parallel unit.
The Gold Reserve Act of 30 January 1934 vested title to monetary gold in the United States. Federal Reserve Banks transferred their gold to the Treasury and received gold certificates in exchange. The Treasury was forbidden to redeem currency in gold for the public. The President set a new official dollar price of $35 an ounce — a devaluation of the gold dollar by statute, not a market print.
At $20.67, one dollar had been a known weight of fine gold. At $35, that weight was cut. The same official stock, marked to the new price, produced a book profit on the Treasury’s accounts. Part of that increment funded the Exchange Stabilization Fund. The metal did not multiply. Official gold is then a government asset at an official price — not a pile the public can test at a window.
A short timeline
The holiday, the order, the contracts, the statute, then the new official price. Not a single weekend.
- 6 March 1933. National bank holiday. Gold payments and exports already constrained.
- 9 March 1933. Emergency Banking Act. Presidential authority over gold in the emergency.
- 5 April 1933. Order 6102: deliver gold coin, bullion, and gold certificates at $20.67.
- 1 May 1933. Delivery deadline in the order. Licenses and exemptions continue.
- 12 May 1933. Thomas Amendment: authority to cut the gold content of the dollar.
- 5 June 1933. Joint Resolution voids gold clauses in contracts.
- 30 January 1934. Gold Reserve Act. Title vests in the United States. Official price $35.
- 1934–1974. Domestic monetary gold holding remains restricted. The official window for foreign governments stays open at $35 until 1971.
The stated rationale
The contemporaneous justification was Depression emergency: stop hoarding, reopen banks, expand the money stock, and raise the domestic price level. Officials argued that gold in private hoards and in bank vaults as coin blocked recovery, and that a higher official gold price would cheapen the dollar in gold terms.
Whether that program worked as advertised is a later argument among economists. The sequence itself is not in dispute: holiday, order, delivery, gold-clause resolution, statute, new official price.
A call on private American gold
The classical gold standard ended as a working international system in 1914, when war finance blocked gold shipment and protected notes from internal drains. That break is about convertibility and metal movement among countries. It is not a domestic recall of coin from American households.
The 1933–34 sequence is a United States statute story. Private monetary gold rights are removed. Title to official gold vests in the Treasury. The official price moves from $20.67 to $35. Americans lose a public claim they had still possessed after 1914.
Bretton Woods, in 1944, defined the dollar against gold at $35 for official convertibility. Ordinary people in the United States did not redeem paper at the Treasury window. On 15 August 1971 the Nixon shock closed the remaining window: foreign official holders could no longer present dollars and demand US gold at the posted price.
They were three different breaks. 1914 ended classical convertibility under the pressure of war, 1933–34 removed the American public’s claim and revalued official gold, and 1971 ended official dollar–gold convertibility for foreign holders. In each case gold stopped being a right a holder could test, which does not make the three events the same act.
After 1933
Americans could not legally hold monetary gold for decades. Licenses covered industry, dentistry, and art. The prohibition lasted until the end of 1974, when statute again allowed citizens to hold gold bullion. Restoration of private holding did not restore a public convertibility contract. The $35 official price was already a bookkeeping fossil. The metal had a market. The dollar did not have a public gold window.
Between 1934 and 1971 the official price still mattered for foreign official holders and for Treasury accounts. It did not matter as a price at which an American could walk in with a note and walk out with coin. When the window finally closed in 1971, it was the $35 price the 1934 Act had set that could no longer be honoured.
Americans kept the paper. The metal went to the Treasury at $20.67 an ounce and reappeared on its books at $35. The notes in their wallets looked the same as before. What those notes could be exchanged for had changed by law.