
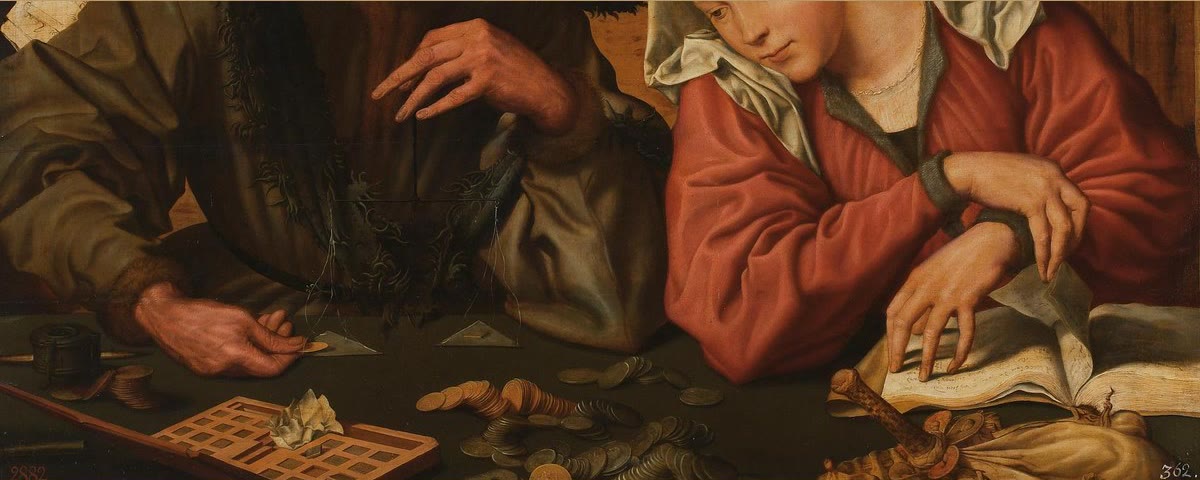
In 1640, Charles I seized merchants’ bullion stored in the Tower mint because the Crown needed cash for war, and depositors who had treated a royal warehouse as safe learned that a sovereign can close the window. After the Restoration, London’s custom shifted toward goldsmiths, private keepers whose running-cash notes could be endorsed onward while the metal stayed put.
Those notes were still claim checks on deposited metal, and once someone else would take the paper in payment, a debt could be settled without the metal leaving the vault. City giro balances, war-bank notes, regency shares, and revolutionary land paper each grew from that habit, on their own dates.
A claim check, not a currency
Someone delivered coin or bullion, the keeper recorded a weight and a fineness, and the paper said that metal could be collected. Until the paper circulated it was a receipt, useful and portable, and still a ticket to a vault.
The ordinary test was whether the holder could still get the metal at the window. Counterparties took the slip because they trusted the warehouse, not because a statute had declared it money, so the legal form stayed a deposit and the economic fact stayed custody.
Later talk of “paper money” is wider than this. The receipt pointed at gold and silver rather than replacing the unit, and merchants used the paper so they would not have to cart mixed specie through the street each time a bill fell due.
The keeper’s reputation was the whole machine at this stage. An honest vault and an open window made the ticket almost as good as coin, and if the keeper lent the metal, or the sovereign seized it, the ticket was only as good as the next rumour.
Private vaults, civic tables, goldsmiths
Late-medieval and early-modern Europe already knew the warehouse model in Italian cities, where money-changers and deposit bankers in Venice, Genoa, and Florence took in coin, kept accounts, and transferred balances for merchants who did not want to settle in bags. Private houses failed when loans and the vault got tangled, and cities then reached for a public table, a bank whose books the bill market had to use.
That civic answer is older than London goldsmith notes. Barcelona’s Taula de Canvi dates from 1401, Venice opened the Banco della Piazza di Rialto in 1587 after private-bank failures, and Amsterdam’s Wisselbank, in 1609, became the model public deposit bank. Public tables and private goldsmiths were parallel answers to the same custody problem, not a single national ladder.
London’s path ran through the mint and then through goldsmiths. After the Tower seizure of 1640, merchants no longer treated a royal warehouse as a safe one, and after the Restoration the goldsmiths took the custom, issuing running-cash notes that could be endorsed onward.
Those notes were still, in form, claims on metal left with a private keeper, but the goldsmiths also lent, and the float — the metal that stayed while the paper moved — became a loan book. In 1672 the Stop of the Exchequer suspended payments on much of that royal debt, and goldsmith-bankers who had treated the Exchequer as a safe asset discovered that a sovereign borrower can close a window too.
When the receipt starts to move
What changed the receipt into money in use was circulation without movement of the metal. Once a third party accepted the ticket in payment, the issuer had issued money in use even if the law still called it a deposit receipt, and the vault need not empty because the paper did the paying.
As long as redemption was ordinary, people held the ticket because it was lighter than coin, not because they had given up on coin. When issue outran what the window could pay, the same paper became a bet on the keeper, a quiet shift from warehouse to bank that did not require a theory of fiat, only a queue the till could not meet.
The warehouse receipt still named metal in a pile, while a bank note promised to pay, often against a mixed reserve and a loan book, and a public-bank balance was a book entry the city or the state had made hard to refuse for large settlement. The first could become the second without a revolution, and the second became the third when settlement was pulled onto a public ledger.
Why a public bank
Private keepers solved a storage problem and then a payment problem, but they did not, by themselves, give a whole market one book everyone had to use. Worn and foreign coin made large bills of exchange a fight over which pile counted, so a public deposit bank could take in mixed specie, credit a standard bank money, and force wholesale payments through its books.
Amsterdam built that table. The Bank of Amsterdam, the Wisselbank of 1609, long had a reputation for not lending — a florin banco as a claim on metal, not on a loan — until concealed lending, made public in the 1780s–1790s, broke that reputation.
England’s later public machine was different again. The Bank of England, chartered in 1694, was born as war finance with a note issue attached rather than as a city giro table, and it stopped paying gold for its notes in 1797 and resumed only in the 1820s.
A short timeline
Civic tables, goldsmith notes, and a war bank — on separate dates.
- 1401. Barcelona’s Taula de Canvi: an early civic deposit table.
- 1587. Venice’s Banco della Piazza di Rialto, after private-bank failures.
- 1609. Bank of Amsterdam: public deposit money for the bill market.
- 1640. Charles I seizes mint deposits in the Tower; London custom shifts toward goldsmiths.
- Mid-seventeenth century. Goldsmith running-cash notes circulate by endorsement; the receipt pays.
- 1672. Stop of the Exchequer; private paper that funded the Crown meets a closed sovereign window.
- 1694. Bank of England charter: war loan and notes — a different public machine from Amsterdam.
Why the handoff matters
Once notes and book money were public, the issuer could be leaned on: a city could borrow against the vault, a crown could borrow against a charter, a regency could fuse a note-issuing bank with a rising company, and revolutionary paper could be tied to confiscated land and issued faster than it was retired. Those steps were possible because the public had already learned to pay with paper claims.
John Law’s Mississippi System broke in 1720: notes and shares under a French regency. The assignats ran from 1789 to 1796 as revolutionary paper with a land story, and Germany’s mark in 1923 was a twentieth-century collapse after war, reparations, and extreme monetization.
All of them rested on the habit the goldsmiths taught London: a slip of paper could settle a debt while the metal stayed where it was. The ticket stayed good exactly as long as the window paid.