
Poland’s central bank closed August 2026 with 648 tonnes of gold on its books — up from about 103 tonnes at the end of 2017. China’s published stock at the end of September 2026 sat near 2,410 tonnes. Canada’s monthly reserve table still prints Gold: 0. Those three lines come from the same kind of document: an official reserve report filed with the IMF or published by the bank itself.
From those reports come the figures people quote — how much gold a country holds, what share of its reserves that gold makes up, how the stock compares with the size of the economy, and who bought or sold in a given month. Central banks move metal under statute, sanctions, and reserve rules. The arithmetic is a state ledger, not a household savings plan.
How gold gets onto the reserve books
The IMF’s International Financial Statistics and related reserve templates ask members to report official gold holdings. The physical quantity is the durable fact: tonnes or troy ounces of monetary gold. A dollar value is then attached so gold can sit beside foreign-currency assets, SDRs (Special Drawing Rights — an IMF reserve asset), and IMF reserve positions in one reserve total.
That dollar value is a reporting convention. Some authorities mark gold near a market price when they compute gold’s share of reserves. Others keep a historical or statutory cost on their own books — the U.S. official book value of $42.22 is the extreme case. A high gold share can mean a large inherited stock, a small foreign-currency book, a mark-to-market revaluation, or recent buying. The share alone does not say which.
World official gold, compiled from those country books plus IMF and ECB lines, is on the order of 36,000 tonnes in recent year-end snapshots (about 35,908 tonnes at end-2025 in the compiled desk). The United States remains the largest single reported stock, 8,133.5 tonnes in the July 2026 World Gold Council / IMF book used in the GDP table further down. Germany, Italy, and France hold large legacy European stocks. China’s published official figure sits above 2,300 tonnes and is widely treated as a floor, not a full count. Russia’s July 2026 line in that same compilation is 2,276.8 tonnes.
Gold as a share of FX and gold reserves
Tonnes and share answer different questions. The share used here is gold valued near a market price, divided by foreign-exchange reserves plus that gold value — the World Gold Council’s usual construction from the IMF’s “total reserves minus gold” line and an end-period LBMA gold price. It does not use the U.S. statutory $42.22 book.
Two published world figures sit a year apart and should not be joined into a trend line. In the Council’s 2025 reserve-manager survey, the prompt stated that gold accounted for 19 percent of total reported reserves — foreign exchange plus gold — in Q3 2024. The Council’s market primer dated 1 April 2026, using IMF COFER and IFS, puts gold at 26 percent of total global allocated reserves by Q3 2025. Different bases, different dates: two prints, not one spliced series.
The same primer splits the 2025 average by group: about 30 percent at developed-market central banks, about 15 percent at emerging-market central banks, against about 4 percent for emerging markets in 2010. Country books show why a world average is a blend. China’s stock is large in tonnes and still small as a share of a very large reserve book: 4 percent at end-2023, 5 percent at end-2024, and 8.9 percent of China’s foreign-exchange reserves in May 2026, per the World Gold Council notes cited with China’s holdings below. Narodowy Bank Polski’s first-quarter 2026 statement put gold at 29.4 percent of Poland’s official reserve assets at the end of March 2026. Poland’s share is higher because its foreign-currency book is smaller, not because it holds more gold than China.
| Dated print | Share | Whose reserves | Source |
|---|---|---|---|
| Q3 2024 | 19% | World reported FX + gold | WGC CBGR Survey 2025 prompt |
| Q3 2025 | 26% | World allocated FX + gold | WGC primer, 1 April 2026 (IMF COFER / IFS) |
| 2010 | ~4% | Emerging-market average | WGC primer, 1 April 2026 |
| 2025 | 15% | Emerging-market average | WGC primer, 1 April 2026 |
| 2025 (DM) | 30% | Developed-market average | WGC primer, 1 April 2026 |
| End-2023 | 4% | China | WGC Gold Demand Trends, FY 2023 |
| End-2024 | 5% | China | WGC Gold Demand Trends, FY 2024 |
| May 2026 | 8.9% | China | WGC, 12 June 2026, citing SAFE |
| March 2026 | 29.4% | Poland | NBP Q1 2026 balance-of-payments note |
A rising share can mean more tonnes, a higher gold price on an unchanged stock, or a smaller foreign-currency book. The share alone cannot tell them apart; the tonnes figure can.
Official gold relative to GDP
Another way to size a gold stock is against the whole economy: take the reported official gold, value it at a named market price, and divide by that country’s nominal GDP. A large vault beside a large economy can look light on this measure; a smaller vault beside a smaller economy can look heavy. It measures weight against output, not the size of the vault.
Tonnes are the World Gold Council compilation drawn from IMF International Financial Statistics, dated 3 September 2026, with country books through 31 July 2026 where those books have appeared — the same July compilation the year-to-date buyer table uses. Market value uses the LBMA Gold Price PM of $4,026.60 an ounce on 31 July 2026, the end-month London price that matches that holdings month, and 32,150.7466 troy ounces per tonne. Nominal GDP is the IMF World Economic Outlook April 2026 current-price dollar line for calendar 2025. Portugal’s 2025 line in that vintage is still an IMF estimate; the vintage’s latest actual year for Portugal is 2024.
On that arithmetic, Portugal’s 382.7 tonnes are about 14.30 percent of its $346.412 billion 2025 GDP — the heaviest row in the table. Switzerland, Italy, and Russia follow in the low teens. The United States has by far the largest stock, 8,133.5 tonnes, yet only about 3.42 percent of $30,767.075 billion. China’s July book of 2,366.3 tonnes is about 1.56 percent of $19,626.247 billion. The same July compilation puts Poland at 640.2 tonnes, about 8.00 percent of its $1,035.586 billion 2025 GDP — close to Germany’s 8.59 percent.
Later months stay out of this division: Poland’s August stock of 648 tonnes and China’s August SAFE print of 76.73 million ounces, about 2,387 tonnes, appear with their own dated books below. Mixing them into a July calculation would produce a percentage no source published.
| Country | Official tonnes | 2025 GDP | Gold / GDP |
|---|---|---|---|
| Portugal | 382.7 | $346.412 bn | 14.30% |
| Switzerland | 1,039.9 | $1,043.544 bn | 12.90% |
| Italy | 2,451.8 | $2,550.111 bn | 12.45% |
| Russian Federation | 2,276.8 | $2,587.938 bn | 11.39% |
| France | 2,437.0 | $3,368.925 bn | 9.36% |
| Germany | 3,349.5 | $5,048.059 bn | 8.59% |
| United States | 8,133.5 | $30,767.075 bn | 3.42% |
| Japan | 846.0 | $4,435.163 bn | 2.47% |
| China | 2,366.3 | $19,626.247 bn | 1.56% |
Gold-to-GDP is a different clock from gold’s share of reserves — the table above. Change the gold price or the GDP year and every row moves: a higher gold price lifts every country’s figure, and a faster-growing economy pulls its own figure down.
Where the bars sit
Reported gold is not always in the reporting capital. For much of the postwar period, European and other official holders kept bars at the Federal Reserve Bank of New York, the Bank of England, and the Banque de France. Custody was a service; title stayed with the owner. Location still matters for politics and for logistics: a bar in New York is not a bar in Frankfurt.
The 2010s brought a documented repatriation wave. The Deutsche Bundesbank’s 2013–2017 programme moved gold from New York and Paris to Frankfurt (300 tonnes from the New York Fed and 374 tonnes from the Banque de France under that plan). De Nederlandsche Bank announced in 2014 that it would bring 122 tonnes from New York to Amsterdam. Austria, Hungary, and others published their own transfers. The Bank of England remains a major custodian for official gold that has not been called home.
A central bank can hold gold at home, at a foreign central bank, or split between the two. What it reports to the IMF is ownership of monetary gold, not the address of the vault.
Where the U.S. official gold sits
The United States also publishes an address list for the gold on its own books: the Treasury’s Status Report of U.S. Government Gold Reserve, carried on FiscalData as the U.S. Treasury-Owned Gold dataset. The report month is August 2026, record date 31 August 2026. The dataset page was last updated 10 September 2026.
Fine troy ounces in the table are the printed lines. Tonnes divide those ounces by 32,150.7466. Each share divides the line by the sum of the report, 261,498,926.241 fine troy ounces. Fort Knox, West Point, and Denver are Mint deep storage — gold bullion bars. Mint working stock is coins, blanks, and miscellaneous gold at Mint locations set aside for coinage. The New York line is Treasury-owned bullion at the Federal Reserve Bank of New York; foreign official bars stored in that building stay on the foreign owner’s reserve book. Display bullion and Reserve Bank coin lines are grouped as other.
| Facility | Fine troy ounces | Tonnes | Share of total |
|---|---|---|---|
| Fort Knox (Mint deep storage) | 147,341,858.382 | 4,582.84 | 56.35% |
| West Point (Mint deep storage) | 54,067,331.379 | 1,681.68 | 20.68% |
| Denver (Mint deep storage) | 43,853,707.279 | 1,364.00 | 16.77% |
| Mint working stock | 2,783,218.656 | 86.57 | 1.06% |
| Federal Reserve Bank of New York | 13,376,987.724 | 416.07 | 5.12% |
| Other (display and coin lines) | 75,822.821 | 2.36 | 0.03% |
| Total | 261,498,926.241 | 8,133.53 | 100% |
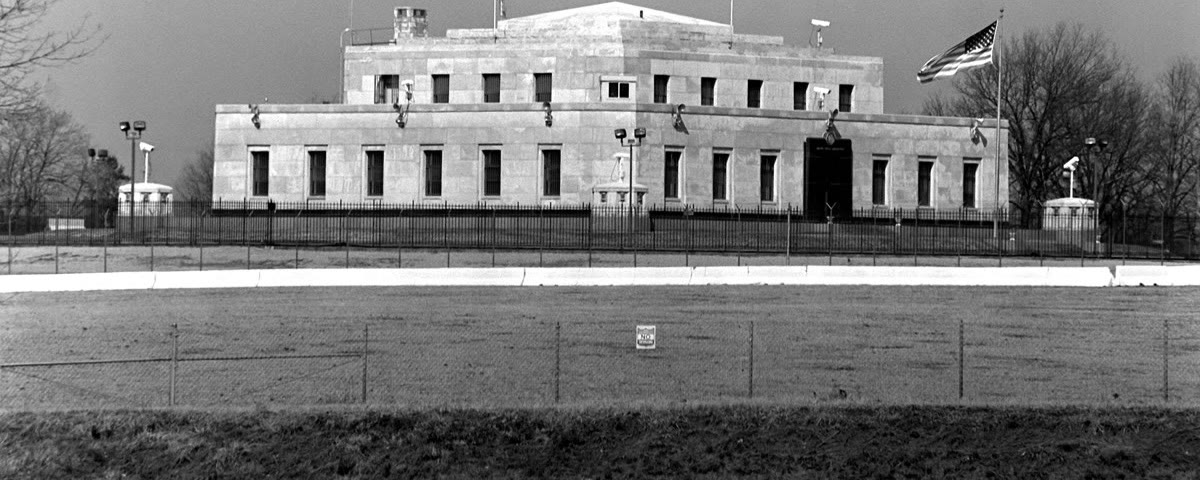
The United States Bullion Depository at Fort Knox took its first gold in January 1937, and the U.S. Mint records that the depository was fully operational that June. These are the same ounces carried at the statutory $42.2222 per fine troy ounce on official gold book value: about 261.5 million fine troy ounces, 8,133.53 tonnes at the conversion above. The 8,133.5 tonnes in the GDP table is that stock rounded to a tenth of a tonne.
Recent official purchases
After years of modest net official demand, the World Gold Council’s annual tallies show a sharp rise in net buying by central banks in the early 2020s. The compiled world net figures used on the desk are 1,080 tonnes in 2022, 1,050.8 tonnes in 2023, and 1,092.4 tonnes in 2024, with a still-open 2025 line. Those are official-sector nets — purchases minus sales — not private investment flows.
Country lines in the same compiled series, drawn from IMF-reported changes, include China (large 2023 additions, then smaller 2024–2025 increments), Türkiye (heavy two-way activity across several years), India, Kazakhstan, Uzbekistan, Czechia (a multi-year buying programme announced in 2023), and Poland. Singapore, Brazil, and Azerbaijan appear as notable 2024–2025 lines. Russia’s large reported additions sit mainly in 2016–2019 in that series.
Reported net buyers, YTD through August 2026
The World Gold Council’s latest monthly compilation of publicly reported official changes — drawn from IMF International Financial Statistics and national central-bank releases — runs through 31 July 2026. In the weeks after that note, a few buyers published August stocks of their own. The table shows both: the latest national figure, and the July figure from the Council beside it.
Reported world purchases in that July compilation were about 130 tonnes. That is the sum of published country lines. It is not the Council’s broader Gold Demand Trends estimate, which also tries to capture unreported official buying. Kazakhstan’s August stock has not yet appeared in a matching national or WGC monthly line, so that row stays on July.
| Country | Reported tonnes | Through | Source |
|---|---|---|---|
| Poland | 98 | August 2026 | NBP president, 10 September 2026 (648 t stock); WGC July 90 t |
| China | 80 | August 2026 | SAFE official reserve assets, 7 September 2026 (76.73 million oz); WGC July 60 t |
| Uzbekistan | 48 | August 2026 | CBU reserves, 7 September 2026 (14.11 million oz as of 1 September); WGC July 40 t |
| Kazakhstan | 29 | July 2026 | WGC monthly (IMF IFS and NBK), through 31 July 2026 |
| Czech Republic | 14 | August 2026 | CNB gold page (85.8 t at end-August); WGC July 12 t |
Reported net official sellers, YTD through July 2026
The same World Gold Council monthly compilation — through 31 July 2026, published 3 September 2026 — also names the largest reported official reductions. Like the buyer figures, each tonne is a change on a central bank’s published books, not a private investment flow.
Two countries dominate the year-to-date sales list. The Central Bank of the Republic of Türkiye sold 1 tonne in July, bringing reported year-to-date sales to 85 tonnes. The Central Bank of Russia sold 6 tonnes in July, bringing reported year-to-date sales to 50 tonnes and its July stock to 2,277 tonnes — the same July book the GDP table rounds to 2,276.8 tonnes. Jordan and Uzbekistan each reported a 1-tonne July reduction in that note; Uzbekistan is still a net buyer for the year, as the buyer table shows. No August seller total has been published yet.
| Country | Reported tonnes | Through | Source |
|---|---|---|---|
| Türkiye | 85 | July 2026 | WGC monthly (IMF IFS and CBRT), through 31 July 2026 |
| Russia | 50 | July 2026 | WGC monthly (IMF IFS and CBR), through 31 July 2026 |
Türkiye’s book has moved in both directions in recent years, so a sale there is one entry in a long two-way record. Russia’s reported sales come after the heavy additions of 2016–2019 noted above.
The Washington Agreement on Gold, 26 September 1999
On 26 September 1999 the European Central Bank published a joint statement on gold. The signatories were the ECB, the euro-area central banks, Sweden’s Riksbank, the Swiss National Bank, and the Bank of England. That statement is the Washington Agreement on Gold.
Annual sales would not exceed about 400 tonnes, and sales over the five years would not exceed 2,000 tonnes. The signatories agreed not to expand gold leasing, or their use of gold futures and options, during that period. The agreement was to be reviewed after five years.
The United Kingdom’s 1999–2002 auctions — Brown’s Bottom, further down — ran while this cap was in force. The reported net official sellers table above names the published reductions through July 2026.
Switzerland drops its gold parity and sells 1,300 tonnes (2000–2005)
On 1 May 2000 the new Swiss currency law took effect, and the franc’s official gold parity of CHF 4,595 per kilogram ended. The Swiss National Bank’s press release of 2 May 2000 records that change. The parity was an official price. How an official gold price differs from a market price is explained under official gold book value.
The Swiss National Bank sold gold from 1 May 2000 under the 1999 Washington Agreement on Gold, in the section above. The sales finished on 30 March 2005. Hildebrand’s speech of 5 May 2005 (BIS copy) puts the total at 1,300 tonnes.
Of that total, 1,170 tonnes counted against the Washington Agreement’s 2,000-tonne quota, and the Swiss National Bank was its largest user. The last 130 tonnes were sold under the follow-up agreement. About 1,290 tonnes remained afterwards, so roughly half the holdings were sold.
Brown’s Bottom: the UK gold sales of 1999–2002
The best-documented official gold sale of recent decades is British. Traders later nicknamed it Brown’s Bottom, after Gordon Brown, then Chancellor of the Exchequer, and the price level at which the sales took place.
On 7 May 1999, HM Treasury announced a restructuring of the United Kingdom’s foreign-currency and gold reserves. The Bank of England, acting as the Treasury’s agent, then ran 17 uniform-price auctions from July 1999 to March 2002. Approximately 395 tonnes of gold were sold. The Bank of England Quarterly Bulletin for Summer 2003 records that the stock then stood around 715 tonnes, with a medium-term aim of around 300 tonnes. At each of the first eleven auctions, 25 tonnes were offered; at each of the last six, 20 tonnes were offered.
The same Bank article puts the average auction price at around $275 an ounce — $274.9 in the footnote that also names the programme’s revenue at approximately $3.5 billion. HM Treasury’s later GOV.UK disclosure, published 31 March 2010, uses the same tonne, auction-count, and dollar-proceeds figures, and adds a contemporaneous sterling figure of about £1.9 billion. The proceeds stayed inside the reserves, reinvested in dollar, euro, and yen interest-bearing assets.
The Treasury’s stated aim was to restructure the reserves — less gold, more foreign currency — so the portfolio held a larger share in interest-bearing currencies. The reserves did not shrink; their mix changed.
The auction clearing price was a market price: dollars per ounce actually paid by successful bidders. The U.S. leftover par of $42.22, explained under official gold book value, is a reporting convention on another ledger. One number is what the auctions fetched; the other is what a Treasury line still writes for ounces it never sold.
China: reported holdings since 2000
China reports official gold as a stock of monetary gold. The People’s Bank of China and the State Administration of Foreign Exchange (SAFE) publish the figure — in tonnes in some announcements, in fine troy ounces on the monthly official-reserve-assets table. The World Gold Council’s country book then carries that stock through IMF International Financial Statistics. These are the figures China reports, not a count of every bar in the country.
For long stretches the published number did not move. At the end of 2000 the IMF/WGC series sat at about 395 tonnes. In April 2009, SAFE’s Hu Xiaolian stated that China had adjusted the stock twice already this century — from 394 tonnes to 500 tonnes in 2001, then to 600 tonnes in 2003 — and that the stock had then reached 1,054 tonnes. That 600-tonne book is the WGC 2005 line. The 1,054-tonne figure held, in the WGC/IMF book, through 2010 and on to early 2015.
In July 2015 the PBoC said the stock at the end of June 2015 was 1,658 tonnes (53.31 million ounces). Monthly SAFE reporting followed. The WGC year-end 2015 line is 1,760 tonnes. A later pause left the book near 1,948 tonnes — 62.64 million ounces at the end of October 2019, per PBoC data carried by Xinhua — and the WGC 2020 year-end line is 1,950 tonnes.
Reported buying resumed and produced the large 2023 addition. The World Gold Council’s Gold Demand Trends for full-year 2023 put the stock at 2,235 tonnes after about 225 tonnes of reported buying, the largest single year of published Chinese additions in the IMF series back to 1977. Full-year 2024 put the stock at 2,280 tonnes after 44 tonnes of reported buying. The WGC/IMF year-end 2025 line is 2,306 tonnes.
The 2026 monthly figures through August are the series the year-to-date buyer table uses. A World Gold Council China note dated 12 June 2026, citing SAFE, put May’s stock at 2,332 tonnes after a 10-tonne month. SAFE’s official-reserve-assets table published 7 September 2026 printed 76.73 million ounces at the end of August 2026 — about 2,387 tonnes. The buyer table rounds the same SAFE/WGC compilation to 80 tonnes through August. SAFE’s official-reserve-assets table published 7 October 2026 printed 77.47 million fine troy ounces at the end of September 2026, up 0.74 million ounces (about 23 tonnes) from August — about 2,410 tonnes, the 23rd consecutive monthly increase. Against the 2,306-tonne end-2025 line, that is about +104 tonnes year-to-date. On the same table the reported dollar value of the gold fell from $350.08 billion at end-August to $323.52 billion at end-September: the ounces rose and the dollar value fell, a price effect (China Daily, 7 October 2026).
| Dated print | Reported tonnes | Source |
|---|---|---|
| End-2000 | 395 | WGC / IMF IFS (PBoC later cited 394 t before the 2001 step) |
| 2003 | 600 | PBoC (Hu Xiaolian, April 2009); WGC 2005 line is the same book |
| April 2009 | 1,054 | PBoC / SAFE; WGC 2010 line holds this plateau |
| End-June 2015 | 1,658 | PBoC, July 2015 (53.31 million oz) |
| End-2015 | 1,760 | WGC / IMF IFS |
| October 2019 | 1,948 | PBoC, 62.64 million oz (Xinhua, 7 November 2019) |
| End-2020 | 1,950 | WGC / IMF IFS |
| End-2023 | 2,235 | WGC Gold Demand Trends, FY 2023 |
| End-2024 | 2,280 | WGC Gold Demand Trends, FY 2024 (+44 t reported) |
| End-2025 | 2,306 | WGC / IMF IFS |
| May 2026 | 2,332 | WGC, 12 June 2026, citing SAFE (+10 t in May) |
| August 2026 | 2,387 | SAFE, 76.73 million oz, 7 September 2026 |
| September 2026 | 2,410 | SAFE, 77.47 million oz, 7 October 2026 |
The long flat stretches are part of the record: years with no reported change, then a jump announced all at once, as in 2009 and 2015. A later month can still revise a rounded tonne.
Treasuries and gold on China’s reserve book, 2026
Mainland China’s reported gold, in the table above, is one line. U.S. Treasury holdings are another, and the two prints do not end on the same day. TIC Table 5, Major Foreign Holders of Treasury Securities, prints China, Mainland at $684.4 billion at the end of December 2025 and $618.0 billion at the end of July 2026. The difference of those two cells is $66.4 billion. The file was posted with the 16 September 2026 TIC release. The gold tonnes are the ones already named above: about 2,306 tonnes at the end of 2025, and about 2,410 tonnes at the end of September 2026, about +104 tonnes from the end-2025 line.
TIC attributes holdings by the country where they are held in custody. The note under Table 5 says securities held in overseas custody accounts may not be attributed to the actual owners. Chinese-owned bonds held through a custodian in Belgium or Luxembourg, for example, are not counted as China. The same cells are fair market value — the market price on the last business day of the month, as TIC Form SLT instructs. On the Treasury daily par yield curve the 10-year was 4.18 percent on 31 December 2025 and 4.75 percent on 31 July 2026. With yields higher, part of the $66.4 billion difference is a lower bond price, rather than sales. The two series cover different end dates: Treasuries through July 2026, gold through September 2026.
| Line | End-2025 | Later 2026 print | Difference of the prints |
|---|---|---|---|
| Treasuries, China, Mainland | $684.4 billion | $618.0 billion (end-July) | −$66.4 billion |
| Reported official gold | 2,306 tonnes | about 2,410 tonnes (end-September) | about +104 tonnes |
Poland: from 103 tonnes to 648
Narodowy Bank Polski (NBP) has been Europe’s most visible gold buyer of the 2020s, and its public statements make the build-up easy to follow.
At the end of 2017 NBP’s reported gold stock was about 103 tonnes. In 2018–2019 the bank bought on the order of 126 tonnes, taking the stock to about 229 tonnes by end-2019. In July 2019 NBP announced that it would transfer 100 tonnes from the Bank of England to vaults in Poland — a custody move, not a purchase. Title was already Polish; the bars changed address.
Buying then resumed in size. IMF-based annual changes in the compiled desk put Poland at about +34 tonnes in 2022, +130 tonnes in 2023, and +90 tonnes in 2024, with further additions in 2025. The desk’s latest Poland stock line of 550 tonnes is the year-end-2025 starting point implied by later official additions, not the 2026 stock.
NBP’s first-quarter 2026 balance-of-payments note put the gold stock at 581.6 tonnes at the end of March 2026, then 29.4 percent of official reserve assets (valued at PLN 319.5 billion on that statement). The World Gold Council’s Gold Demand Trends for the second quarter, compiled from IMF and central-bank reports through 30 June 2026, puts the stock at 632 tonnes after about +51 tonnes in the quarter and about +82 tonnes in the first half. The Council’s 3 September 2026 monthly compilation, through 31 July 2026, puts the stock at 640 tonnes, after about +8 tonnes in July and about +90 tonnes year-to-date.
On 10 September 2026, NBP’s president stated that the stock at the end of August 2026 was 648 tonnes, valued at PLN 344.8 billion at then-current prices. That is about +8 tonnes in August and about +98 tonnes year-to-date against the desk’s 550-tonne end-2025 starting point: 550 + 90 reaches the end-July 640; 550 + 98 reaches the end-August 648.
The same WGC notes record NBP’s public stock aim of 700 tonnes, with gold then about 28 percent of total reserves. An earlier NBP communications line had named a reserve-share aim in the region of 20 percent; the March 2026 statement already sat above that share. Governor Adam Glapiński’s remarks in this period treated gold as a long-term reserve asset, not as a trading book.
Canada: Gold: 0 on the official book
Canada’s reserve table is unusual among large economies: its gold line reads zero, the end of a sell-down that ran for decades.
Finance Canada’s monthly Official International Reserves tables still print Gold: 0. The release dated 6 August 2026, covering 31 July 2026, puts total official international reserves at US$127,038 million and lists the gold cell as 0. Earlier 2026 monthly tables in the same series, including June and May, show the same. The Bank of Canada’s weekly international-reserves snapshot uses the same Gold: 0 line.
Contemporary reporting of the close-out — including CBC’s March 2016 coverage of Finance Canada’s monthly figures — put the peak stock in the 1960s at more than 1,000 tonnes. By 2003 the published stock was about 3.4 tonnes. The last disposals were coin sales: Finance Canada’s February 2016 Official International Reserves footnote records 21,851 ounces of gold coins sold for settlement in February, with holdings at 77 ounces on 29 February 2016. CBC’s reporting of the same Finance releases names earlier coin sales of 41,106 ounces in December and 32,860 ounces in January. The February table already showed the gold value as 0 in millions of U.S. dollars — the remaining ounces were too few to register at that scale.
The other G7 books tell a different story. The same July 2026 World Gold Council / IMF compilation used in the GDP table still shows large reported stocks for the United States (8,133.5 tonnes), Germany (3,349.5 tonnes), Italy (2,451.8 tonnes), France (2,437.0 tonnes), and Japan (846.0 tonnes), while Canada’s reserves are held almost entirely in foreign currencies and other non-gold assets.
A rising share can be new buying or simply a higher gold price. A repatriation moves bars without changing who owns them. A sale like the 1999–2002 UK auction programme swaps gold for currency inside the same reserves. Canada’s printed Gold: 0 is what a long sell-down looks like once it is finished.
The U.S. figure of $42.22 is a separate accounting convention, explained under official gold book value. The 1971 end of dollar–gold convertibility is told in Sound Money History.