
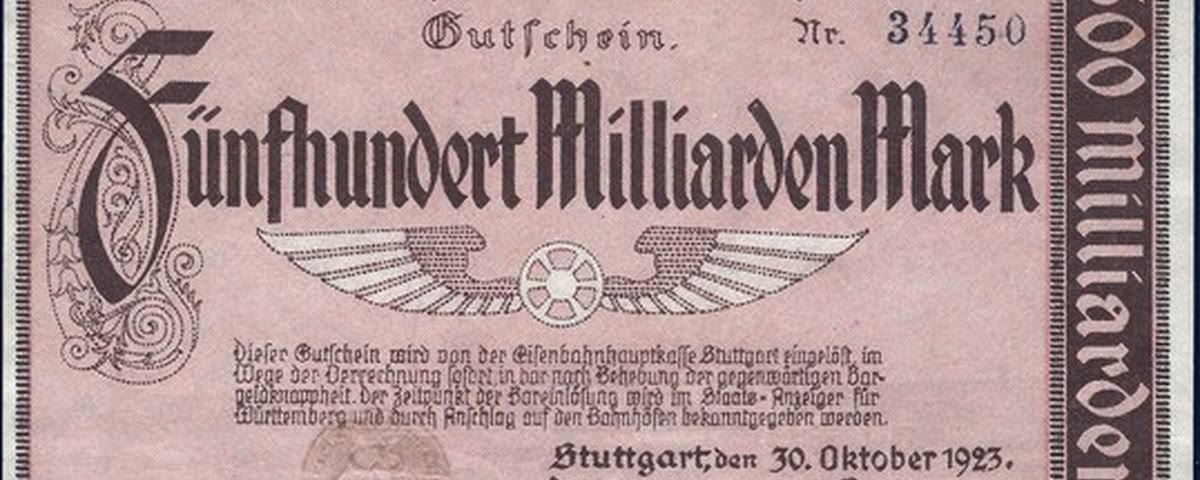
If the same hour of work buys less bread, less rent, or less metal over the years, the unit has weakened — even when no wheelbarrow appears in the street. That loss is purchasing power. Prices are only the surface. A rise of 50% or more in a month is a special case of the same fact, not a separate species of money.
The unit, not the index
The question underneath is whether the stock of money is growing faster than the goods and claims it is asked to measure. An hour of work is a useful check, with or without a crisis.
Consumer-price indexes and wholesale indexes document the erosion. They do not invent it. Basket choice, quality adjustments, and the base year change how a series reads. They do not change what the unit buys.
Weimar 1923 is the extreme, and it gets pasted onto every mild rise in an index. A two-percent annual rise and a fifty-percent monthly rise share a channel when the stock is discretionary. They do not share a speed.
Three reasons a price moves
Prices rise because goods are scarce, because demand shifts, or because more units chase the same things. A year usually has all three. The one that matters for the unit is the last: issue without cost turns the stock into a policy choice.
A hard unit does not freeze bread against rent. A failed harvest, war damage, and a shift in demand still move particular prices while convertibility holds. Wartime scarcity can lift food under a gold standard without rewriting the ounce.
When the issuer can expand the stock as policy, a fiscal gap is closed with new units. Tax arrives later, in weaker money. Real cash balances fall, people spend faster, and velocity rises. That loop is the mechanics of a severe episode.
What the unit buys
Check a basket of goods, an hour of common labor, a weight of metal. If the basket shrinks for the same nominal wage, purchasing power fell. If metal rises sharply in the unit and the cost of mining it did not jump overnight, the unit is the thing that weakened.
A premium, a tax, or a local shortage can move one price. The check is the unit across many goods. Whether the issuer can expand the stock as policy is the line between hard money and fiat.
Greenbacks in the American Civil War traded at a gold premium in New York. That premium was paper measured against metal, quoted daily. Resumption later closed it. The history is greenbacks and the Civil War.
A lender who expects the unit to weaken asks for more of it back. Bond prices move with that expectation. The first object is still what the unit buys.
Hyperinflation is a case
Hyperinflation is usually marked when prices rise on the order of 50% or more in a month. It is a phase. Germany crossed that line in mid-1922. By autumn 1923 the paper mark had ceased to work as a store of value or a unit of account.
Wheelbarrows and wallpaper notes are evidence that people refused to hold balances. They are not the cause. In Germany the chain ran from war finance and a missing gold stop to fiscal gaps and a central bank that turned Treasury paper into marks.
Assignats in revolutionary France, and Law’s System in 1720, are other paper collapses, with their own dates and their own instruments. The rhyme is the mechanism. Merging the episodes erases the centuries between them.
Stopping one usually takes three things at once: a new unit, a fiscal stop, and a credible refusal to print for the treasury. Germany’s Rentenmark in November 1923 had all three. A new name on the note, without the second and the third, only restarts the clock.
After the shortage passes
A war or a failed harvest can lift prices under the hardest coinage ever minted. Scarcity and a shift in demand are real. What a growing money stock explains is the rise that keeps going after the shortage has passed, because the unit itself is being multiplied.
A shortage lifts some prices and then eases. A weakening unit lifts nearly all of them and does not ease. The thing being measured has changed.
The slow case and the fast one
Most of it is slow. A few percent a year is hard to feel in a week and easy to feel across a working life. A saver who holds the unit for thirty years at three percent a year ends up with well under half the purchasing power he started with. Nobody queues at a bank for that. It shows up in wages that have to be renegotiated, and in savings that have to sit somewhere else.
The fast case is rarer and louder. It is the one people remember, and it ends with a new unit. Both run through the same channel. What separates them is how quickly the holder notices, and how quickly he stops holding.