
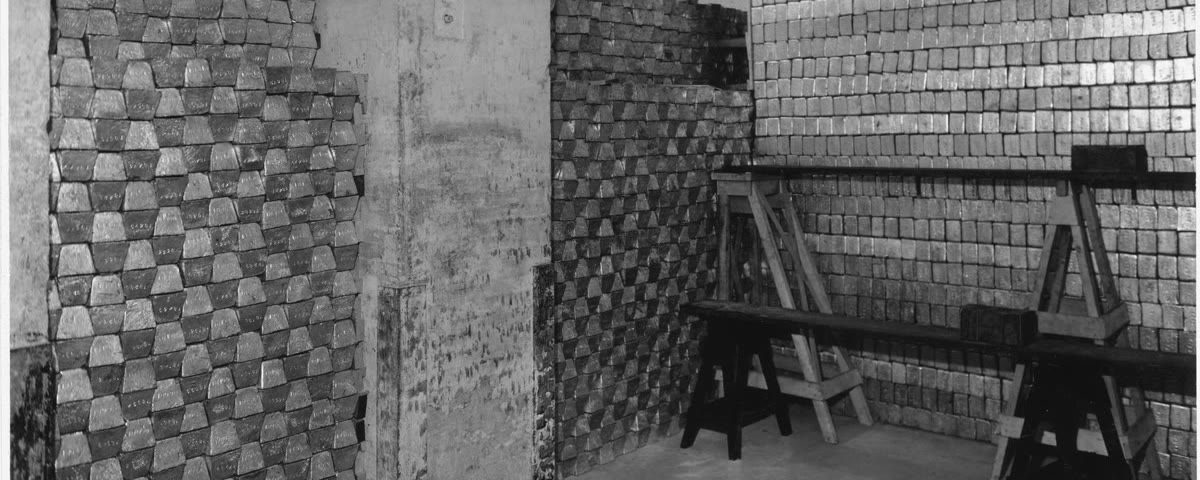
A vault photograph and a teller window are not the same claim. A note you can hand in for a defined weight of metal is a contract. Gold sitting in a vault, with no public right to ask for it, is a slogan — or, at best, a line on a reserve sheet. “Backed” is the word people use for both.
A contract, or a slogan
Redeemability is testable. Either a holder can demand the metal at a known price, or they cannot. Reserves on a balance sheet, without that right, do not make the unit hard.
A classical convertibility rule said: present the note, take the weight. The vault mattered because the public claim could empty it. A modern central-bank gold pile without that claim is a portfolio. It is not the same contract.
“Full faith and credit” names taxes and legal tender. That can be a strong fiscal claim. It is not metal.
Without a presentment right, confidence is a story about the issuer. It is not a contract a holder can enforce at a window on a working day.
Bonds, dollars, and a mortgage
Covering a note issue with government bonds is a claim on a tax office. A gold-exchange standard, as after Bretton Woods, backed some currencies with dollars and dollars with official gold — not with coin in the public’s hand. The Rentenmark was “backed” by mortgages: an accounting and political device to stop the press, not a pile of gold at the window.
The official book value of U.S. gold is still carried at a statutory dollar price far from the market. That official gold book value is an accounting convention. Nobody redeems anything at that price.
A chart of central-bank gold reserves answers how much metal the state holds. It does not answer whether a private holder can present notes and take metal. The chart can rise beside a domestic unit that is pure fiat.
The window
Under a working gold or silver standard, banks and treasuries published the rules: which notes, which weights, which offices. The public test was the window. When the window closed for a war or an emergency, the note might still say “gold.” The contract had changed.
The 1933 U.S. gold recall is the other side of the same fact. A gold dollar can have the public claim removed by statute. Americans lost monetary gold years before 1971, when the window closed for foreign official holders.
Bretton Woods then limited the remaining gold link to those official holders, at $35 an ounce. Retail Americans were not walking into a Treasury window for coin. Calling those years gold-backed, without naming who could redeem, is how the slogan swallows the contract.
Warehouse receipts and early bank notes started as claims on deposited metal. That is how paper money began. When the receipt stops being payable in metal on demand, the instrument has changed category even if the engraving lags behind.
Reserves without a public claim
A treasury can hold metal, foreign exchange, and securities while the domestic unit is fiat. The reserves may steady an exchange rate, satisfy a creditor, or signal prudence. None of that restores a holder’s right to metal unless the law says so.
Mortgage “backing,” land “backing,” and commodity baskets in a propaganda sheet usually mean an accounting cover, so the new issue looks limited. The Rentenmark’s mortgages were that device. Holders could not demand a farm at the window.
Two questions cut through the word. Backed by what instrument, and who may present the claim? “Gold in a vault, for the central bank’s own books” is reserves. “A defined weight, on demand, for the holder” is a contract.
A fractional reserve against a redeemable note is a banking fact: the note is still a claim on metal, and it can be run. That is a different structure from a non-redeemable unit whose issuer happens to own some gold.
Why the vault still matters
States use reserves. They settle debts between governments, defend an exchange rate, and reassure creditors in a crisis. The same tonnes can sit behind a public right or behind a closed door. Only one of those arrangements puts a key in the holder’s hand.
A holder with a contract can walk to the window. A holder with a slogan can read about the vault.
What the word used to mean
For most of the nineteenth century the word was not a feeling. A note was backed if it could be exchanged for coin, and the bank that could not pay could be run. The wartime suspensions of 1914, the American recall of 1933, and the closing of the official window in 1971 kept the word and removed a holder from the contract.
By the end it described a mood about the issuer rather than a right against it. Who can present what, for how much, is the older meaning, and it is the one that makes those years readable.